Short answer: For new-to-credit borrowers outside India’s metros, app-first lending loses on unit economics, through low discovery, high onboarding drop-off, weak verification and costly collections. An assisted model performs better: a trusted local agent, vernacular AI and a fully digital back end. For this segment, “phygital” isn’t a halfway house on the road to digital. It’s the destination.
Indian lending has spent a decade optimising for the borrower who downloads an app, completes video KYC in English and repays by auto-debit. That borrower is now well served, and fiercely contested.
The numbers show the strain. TransUnion CIBIL’s Unlocking Access report (July 2026) finds that new-to-credit consumers’ share of retail originations fell from 32% in the March 2017 quarter to 13% in the March 2026 quarter. Lenders have drifted towards the credit-tested borrower.
The physical last mile is under pressure too. Business correspondent outlets fell from about 15.5 lakh in FY24 to about 13.1 lakh in FY25, per RBI data, and RBI has since proposed an overhaul of the BC framework to restore rural reach.
The next wave looks different. A kirana owner in a tier-4 town. A first-time borrower who shares a phone with family. A farmer who’d rather talk than type. These customers aren’t anti-digital. They’re anti-unassisted: they want a person they trust, in a language they speak, at the moment of commitment.
Lenders who keep pushing app installs at this segment will keep paying for leads that never book. Lenders who redesign the funnel around assistance will grow where others stall.
Why does app-first lending leak with new-to-credit borrowers?
The leak isn’t in one place. It compounds across every stage of the funnel, and each stage has a different root cause.
| Funnel stage | Where app-first breaks | What assistance changes |
|---|---|---|
| Reach | Borrower never discovers or installs the app | An agent the borrower already knows brings the product to them |
| Onboarding | Drop-off at KYC, document upload and OTP steps | The agent guides each step on their device, in person |
| Understanding | Terms in English or formal language the borrower doesn’t trust | Explanation in the borrower’s own language, by voice |
| Lead quality | Unqualified applications clog underwriting | Agent pre-screens; leads arrive validated |
| Decision | Thin-file borrowers get declined or stuck in manual review | Richer, verified data captured at source improves the decision |
| Collections | Remote reminders are easy to ignore | Relationship-led follow-up through the same trusted channel |
The pattern is consistent: every stage where app-first relies on the borrower acting alone is a stage where assistance recovers conversion. Digital back ends still do the heavy lifting. The difference is a human at the front.
Isn’t assisted lending more expensive? The real economics
On a cost-per-lead view, yes. An agent costs more than a digital ad. But cost per lead is the wrong metric. What matters is cost per booked, performing loan, and that’s where the comparison flips.
Cost per booked loan is driven by four ratios:
Cost per booked loan = Acquisition cost ÷ (Lead-to-application × Application-to-approval × Approval-to-disbursal) + Servicing and collections cost
App-first wins on the numerator: cheap acquisition. Assisted wins on the denominator: far more of each lead becomes a loan, and that loan performs better. For new-to-credit segments, small improvements at each of three conversion stages multiply, which is why the denominator usually dominates.
Three further effects tilt the economics towards assistance:
- Verification quality. Data captured in person, at source, reduces fraud and rework downstream.
- Collections cost. A relationship channel lowers the cost of keeping a loan current.
- Cross-sell. The same agent can offer savings, insurance and repeat credit, spreading acquisition cost across products.
The practical test for any lender: model both funnels on your own data, stage by stage, and compare cost per performing loan at month 12. That comparison, not cost per lead, should decide channel budgets.
How Trustt powers assisted digital lending
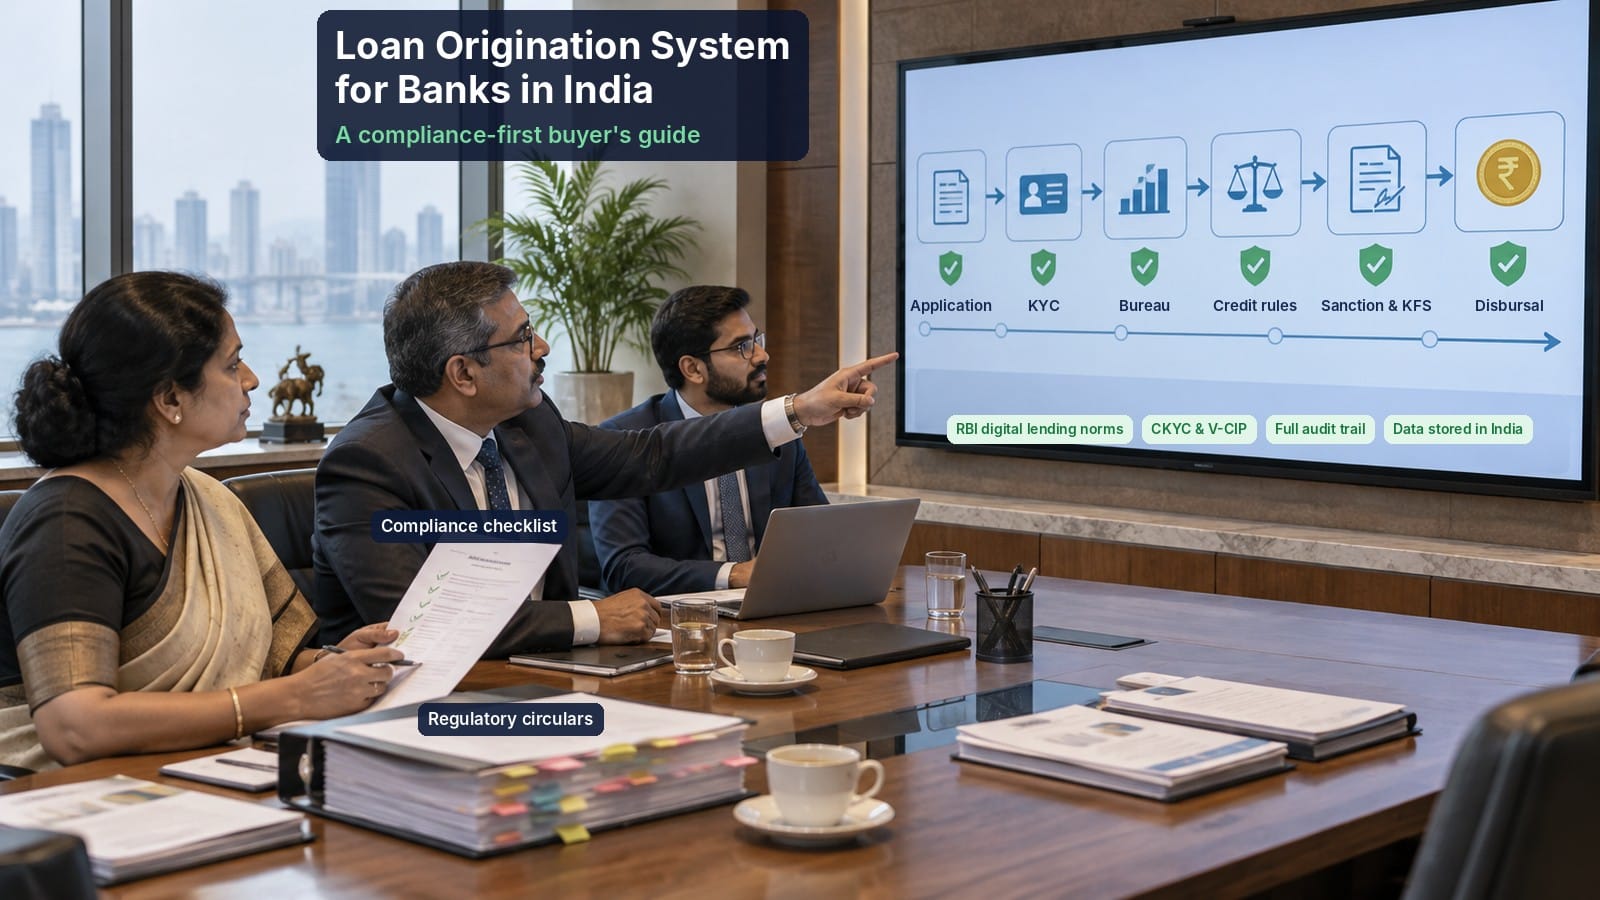
Assisted lending only works if the agent is backed by a fully digital engine. Otherwise you’ve just rebuilt the branch, with paper. Trustt provides that engine, end to end.
| Funnel stage | Trustt capability |
|---|---|
| Reach | Digital Distribution Platform lets a bank onboard business correspondents and DSAs. An agent can go live in about ten minutes, under the bank’s own brand |
| Lead quality | Deduplication, consent and attribution are built into the distribution flow |
| Onboarding | Digital Identity Suite supports agent-assisted eKYC and verification at source |
| Understanding | TrusttAI, including our voice-first assistant, works in Indian languages such as Hindi, Tamil and Marathi |
| Decision | Loan Origination System and Business Rules Engine turn agent-captured data into consistent, explainable credit decisions |
| Servicing and collections | Loan Management System keeps the loan on one digital record from disbursal to closure |
Trustt’s lending platform already supports group, agri and assisted lending in local languages, and the same agent who originates a loan can also open accounts, sell insurance and run AePS transactions.
It matters for compliance too. Under the RBI (Digital Lending) Directions, 2025, a lender stays responsible for the conduct of its lending service providers. Running agents on one platform, with consent and an audit trail, makes that responsibility manageable at scale.
The point isn’t any single module. It’s that the agent in the field and the credit team at head office work on one connected journey, with no re-keying, no paper handoffs and one view of the borrower.
That’s how a lender gets the conversion of an assisted model with the cost discipline and control of a digital one.
What should lending CXOs do next?
- Segment honestly. Separate borrowers who self-serve well from those who need assistance. Don’t run one funnel for both.
- Change the metric. Measure channels on cost per performing loan at month 12, not cost per lead.
- Map your leaks. Find the stage where new-to-credit applicants drop off most, and put assistance there first.
- Equip agents digitally. Give field partners the same verification, decisioning and tracking tools as your digital channel.
- Lead with language. Make vernacular, voice-first support the default for this segment, not an add-on.
- Keep one record. Ensure field and back office see the same borrower, the same status and the same history.
India’s next wave of credit growth will come from borrowers who are digital in their payments and personal in their trust. The lenders that serve both sides of that will own the segment.
Building for Bharat’s next borrowers? Talk to Trustt about an assisted digital lending journey, from agent network to loan book, on one platform.
Frequently asked questions
What is assisted digital lending? A lending model where a trusted agent, such as a banking correspondent or field partner, guides the borrower through a fully digital journey, from onboarding and KYC to disbursal and repayment.
Why does app-first lending struggle with new-to-credit borrowers? Because it relies on the borrower acting alone at every step. Low discovery, onboarding drop-off, language barriers and thin credit files all compound across the funnel.
Is assisted lending more expensive than digital lending? It costs more per lead, but it can cost less per booked, performing loan because far more leads convert and loans tend to be better verified.
What role do business correspondents play in lending? They extend a lender’s reach into areas without branches, help borrowers complete digital journeys and support ongoing servicing and collections.
How does Trustt support assisted digital lending? Trustt connects its Digital Distribution Platform, Digital Identity Suite, TrusttAI and Digital Lending Platform (LOS, BRE, LMS) so agents in the field and credit teams work on one digital journey.
About the author
Gautam Bandyopadhyay is CEO & Co-Founder of Trustt, the AI banking platform that Indian banks, NBFCs and fintechs use to run lending, partner distribution, digital identity and AI agents on one configurable core.
Before co-founding Trustt (formerly Novopay), Gautam held roles across product management, consulting, global delivery and innovation at Infosys Finacle. As Head of Innovation, he set up the Finacle Innovation Hub and added two products, Finacle Inclusion Solution and Finacle Digital Commerce, the platform behind Airtel Money. Connect with Gautam on LinkedIn.
Trustt: Technology you can bank on!